When saving for retirement, individual retirement accounts (IRAs) offer incredible tax advantages that can accelerate your wealth creation. However, deciding between a Roth IRA and a Traditional IRA is one of the most common dilemmas beginners face.
Both accounts allow you to invest in stocks, index funds, and ETFs, but they are taxed at completely opposite ends of your investment journey. Choosing the right IRA depends on your current income, your expected future tax bracket, and how you want to access your wealth down the road.
1. Traditional IRA: Tax Break Today, Taxes Later
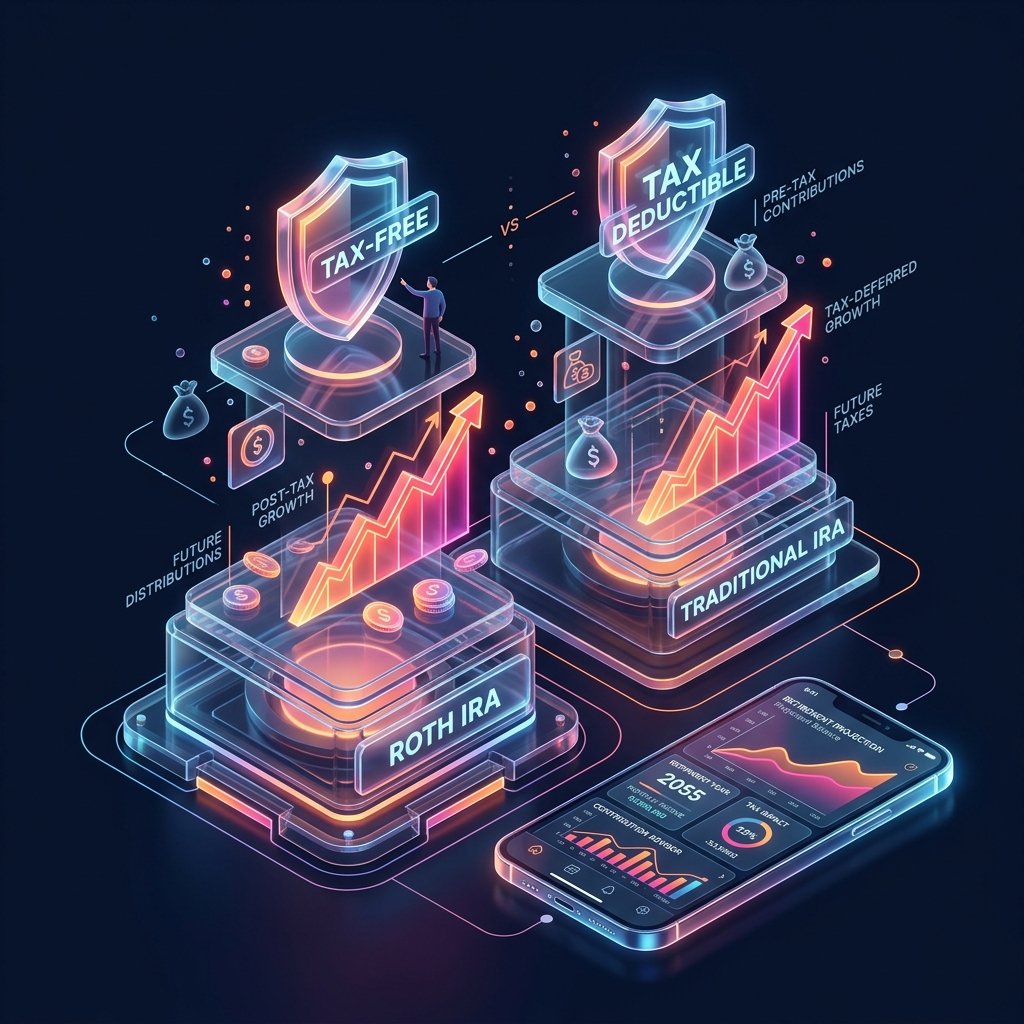
A Traditional IRA gives you an upfront tax deduction in the year you make the contribution, but you pay taxes when you withdraw the money in retirement.
- Tax Treatment: Contributions are often 100% tax-deductible in the year you make them (subject to income limits if you have a workplace retirement plan). Your money grows tax-deferred.
- Withdrawals: When you retire and start withdrawing funds (after age 59½), every dollar withdrawn is taxed as ordinary income at your future tax rate.
- Required Minimum Distributions (RMDs): Starting at age 73, the IRS forces you to take annual required withdrawals, whether you need the cash or not.
2. Roth IRA: Taxed Today, 100% Tax-Free Later
A Roth IRA flips the Traditional model on its head. You contribute after-tax dollars today, but every dollar of growth and every future withdrawal in retirement is 100% tax-free.
- Tax Treatment: You receive zero tax deductions today. You contribute money that has already been taxed.
- Withdrawals: Your contributions and investment earnings grow completely tax-free. When you take withdrawals in retirement (after age 59½), you pay $0 in federal or state taxes.
- Penalty-Free Contributions Access: Because you already paid taxes on your principal contributions, you can withdraw your initial contributions (not the earnings) at any time, for any reason, penalty-free and tax-free.
- No RMDs: Roth IRAs have no required minimum distributions during your lifetime, making them an incredible wealth transfer tool for heirs.
Traditional IRA vs. Roth IRA: Side-by-Side Comparison
| Feature | Traditional IRA | Roth IRA |
| Tax Benefit | Upfront tax deduction now | Tax-free growth and withdrawals later |
| When Do You Pay Taxes? | Upon withdrawal in retirement | Today (Post-tax contributions) |
| Withdrawal Rules (Age 59½+) | Taxed as ordinary income | 100% Tax-Free |
| Early Access to Principal | Taxes + 10% penalty | Withdraw contributions anytime penalty-free |
| Required Minimum Distributions | Yes (Starts at age 73) | None |
| Income Eligibility Limits | No limit to contribute (Deduction limits apply) | Income limits apply to contribute directly |
Which One Should You Choose?
- Choose a Roth IRA if: You are early in your career, currently in a lower tax bracket than you expect to be in at retirement, or want maximum flexibility to access your principal contributions if needed.
- Choose a Traditional IRA if: You are currently in your peak earning years, sit in a high tax bracket today, and want an immediate tax deduction to lower your current taxable income.
Key Takeaways
For young investors and 20-somethings starting out, the Roth IRA is almost always the winner. Paying taxes on a lower salary today in exchange for decades of tax-free growth and tax-free retirement income is one of the greatest tax deals in personal finance.
Disclaimer: This content is for educational and informational purposes only and does not constitute formal tax or financial planning advice.