Budgeting gets a bad reputation. For most people, it brings to mind tedious spreadsheets, strict restrictions, and the guilt of spending money on the things they enjoy. But managing your money doesn’t have to feel like a punishment.
If traditional, line-item budgeting feels too overwhelming, the 50/30/20 budgeting rule is the perfect solution. Designed to be simple, flexible, and sustainable, this intuitive framework ensures you cover your essentials and build wealth without giving up your lifestyle.
What Is the 50/30/20 Budgeting Rule?
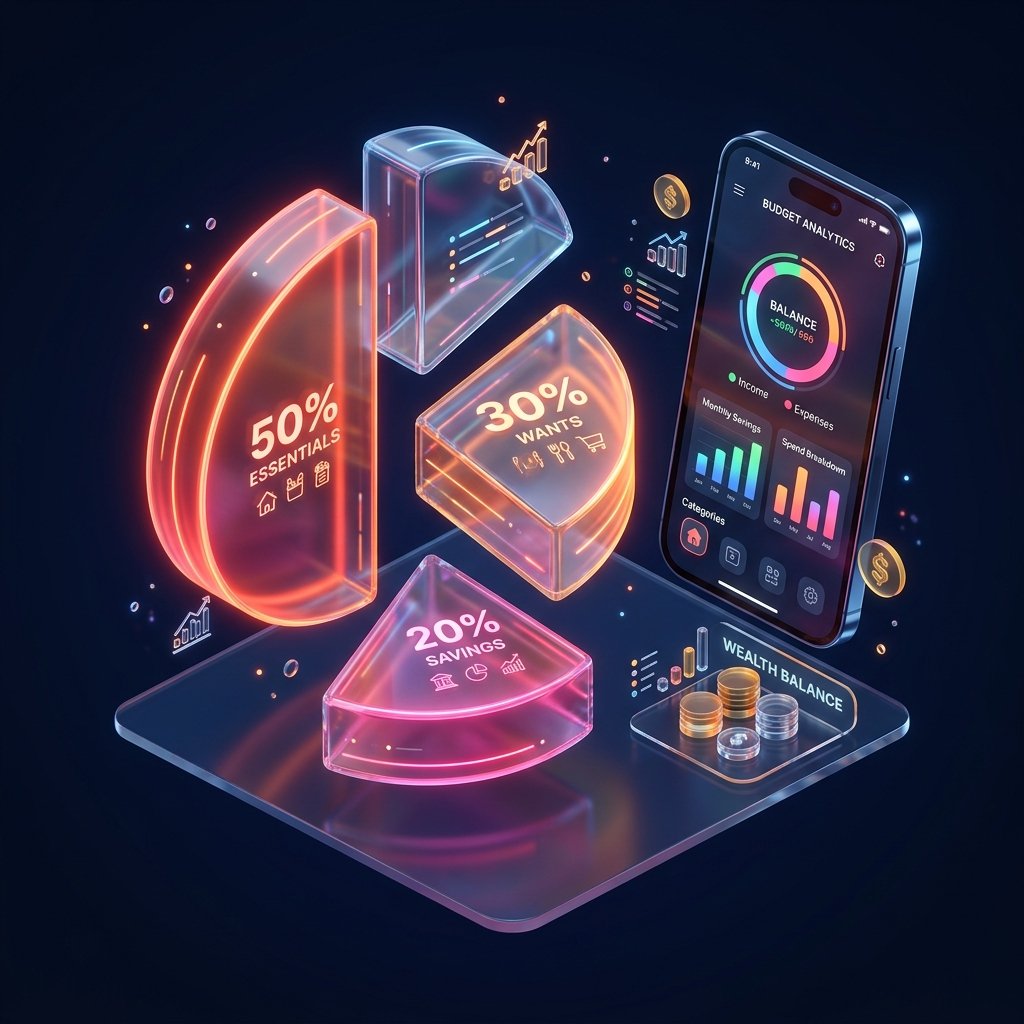
Popularized by Senator Elizabeth Warren in her book All Your Worth: The Ultimate Lifetime Money Plan, the 50/30/20 rule divides your after-tax (take-home) income into three clear categories:
- 50% for Needs
- 30% for Wants
- 20% for Savings & Debt Repayment
By focusing on high-level percentages rather than tracking every dollar, you gain total clarity over where your money goes each month.
Category 1: 50% for Needs (Essential Expenses)
Needs are the non-negotiable expenses you must pay to maintain basic living conditions and employment. Half of your monthly take-home pay should go toward these essentials.
What counts as a Need?
- Housing (Rent or Mortgage payments)
- Utilities (Electricity, water, gas, internet)
- Basic Groceries (excluding dining out)
- Transportation (Car payments, gas, public transit)
- Insurance (Health, auto, renters/homeowners)
- Minimum debt payments (minimum credit card or loan payments)
Tip: If your total needs exceed 50% of your take-home pay, look for ways to downsize high fixed costs, such as switching internet providers, finding a roommate, or refinancing loans.
Category 2: 30% for Wants (Lifestyle & Fun)
This is where the 50/30/20 rule shines over traditional budgets. It explicitly grants you permission to spend up to 30% of your income on items that improve your quality of life, without any guilt.
What counts as a Want?
- Dining out, coffee runs, and food delivery
- Hobbies, entertainment, and concerts
- Subscriptions (Netflix, Spotify, gym memberships)
- Vacations and travel savings
- Shopping for non-essential clothing or gadgets
Tip: Wants are items you choose to spend money on. If money gets tight, this is the first category you scale back.
Category 3: 20% for Savings & Wealth Building
The final 20% is dedicated strictly to building your future self’s net worth and eliminating high-interest debt beyond minimum payments.
What counts as Savings?
- Building an Emergency Fund (3 to 6 months of expenses in an HYSA)
- Retirement contributions (Roth IRA, traditional IRA, or 401(k))
- Stock market investments (Low-cost index funds, ETFs)
- Extra debt payoff (Targeting high-interest debt like credit cards)
Tip: Pay yourself first! As soon as your paycheck hits your account, automatically route this 20% directly into your savings and investment accounts before spending on needs and wants.
How to Calculate Your 50/30/20 Budget (An Example)
Let’s look at how this works in real life with an example of a $4,000 monthly take-home salary:
- Needs (50%): $4,000 × 0.50 = $2,000/month for rent, groceries, and bills.
- Wants (30%): $4,000 × 0.30 = $1,200/month for entertainment, dining, and hobbies.
- Savings (20%): $4,000 × 0.20 = $800/month for investments and emergency reserves.
3 Quick Steps to Implement the 50/30/20 Rule Today
- Calculate Your Net Income: Find your total monthly income after taxes and payroll deductions.
- Review Last Month’s Spending: Group your recent purchases into Needs, Wants, and Savings to see your baseline percentages.
- Automate Your Cash Flow: Set up automated transfers on payday for your 20% savings so you spend what is left without stressing.
Key Takeaways
The 50/30/20 rule gives you a balanced roadmap to manage your present lifestyle while securing your financial future. It removes friction, eliminates overthinking, and allows you to enjoy your money with total confidence.
Disclaimer: This content is for educational and informational purposes only and does not constitute formal financial advice.